The Complete Growth Platform for Independent Advisors — Unlimited Reports, Lead Gen, Support, Training & More|
Trusted by 8,000+ Advisors with 214,000+ Reports Generated
|See Stonewood in Action|
The Complete Growth Platform for Independent Advisors — Unlimited Reports, Lead Gen, Support, Training & More|
Trusted by 8,000+ Advisors with 214,000+ Reports Generated
|See Stonewood in Action|
You might guess fees or performance, but the data actually tells a different story. In a Morningstar study of people who had fired a financial advisor, the top reason was the quality of advice and service (32%). Next came the quality of the relationship (21%). Cost came third at 17%, and unhappiness with returns was 11% [1].
That’s good news for growth-minded advisors.
The quality of advice and strength of your relationships are both things you control. But they take focused efforts – and often the right tools.
This guide focuses on client engagement strategies for financial advisors that can drive client satisfaction and stickiness. Each one is backed by recent research, and each one can start with your next client meeting.
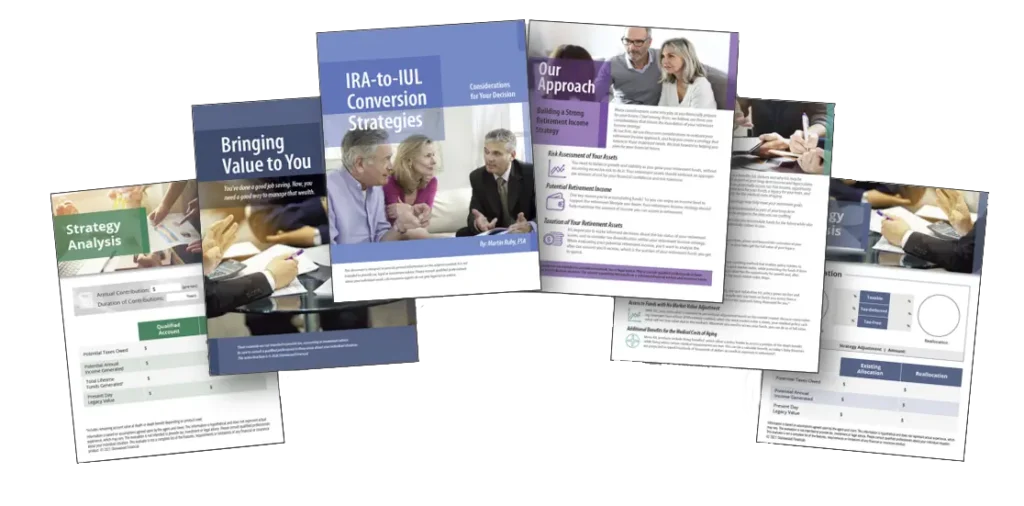
Close More Business with Stonewood Reports
Easy to run. Easy to present. Pick the report that fits your next client conversation and we'll send a sample to your inbox immediately.
Roth Done RightTax & IRMAA Analysis
Annuity AlphaFIA vs. Managed Account
Legacy Done RightLife Insurance Analysis
Total Tax BurdenRetirement Tax Snapshot
Key takeaways
Lead with taxes. In a 2025 Nationwide survey, 54% of savers said they’d switch to a professional who could help them plan for taxes in retirement [2].
Set a contact rhythm. 79% of clients in a YCharts survey want to hear from their advisor at least every three months [3].
Make reviews about the next decision, not last quarter. IRMAA, temporary deductions and RMDs give each review a reason to happen.
Give value before you ask. Kitces Research found the typical practice gets 62% of new clients from client referrals – but you have to ask for them in a way that doesn’t reduce referral volume [4].
Bring in the spouse and heirs. Only 20% of affluent heirs who already inherited kept their benefactor’s advisor [5].
What client engagement means for advisors
Client engagement is how often, and how usefully, clients interact with you between big decisions. An engaged client opens your emails, shows up for reviews, asks questions and tells friends about you.
Of course, engagement isn’t the same as contact. A monthly newsletter 60% of your clients read is engagement. A monthly newsletter that hits inboxes and barely gets opened is simply contact. So how do you drive real engagement with your clients?
Strategy 1: Lead with a topic driving client concern: Taxes
Retirees have a lot on their minds – and increasingly, taxes are front and center in their concerns.
A 2025 Nationwide survey found 58% of savers fear what tax rates in retirement could do to their income, and 59% wish they’d prepared better for taxes in retirement [2].
The best news for independent financial advisors? 54% said they’d switch to a financial professional who could help them plan for those taxes [2].
Clients want help when it comes to taxes in retirement. In Cerulli research with Parametric, nearly 70% said it’s important that their provider helps reduce their tax bill. Yet just under half of advisors focus on tax mitigation as a core part of their retirement planning [7].
That gap is your opportunity.
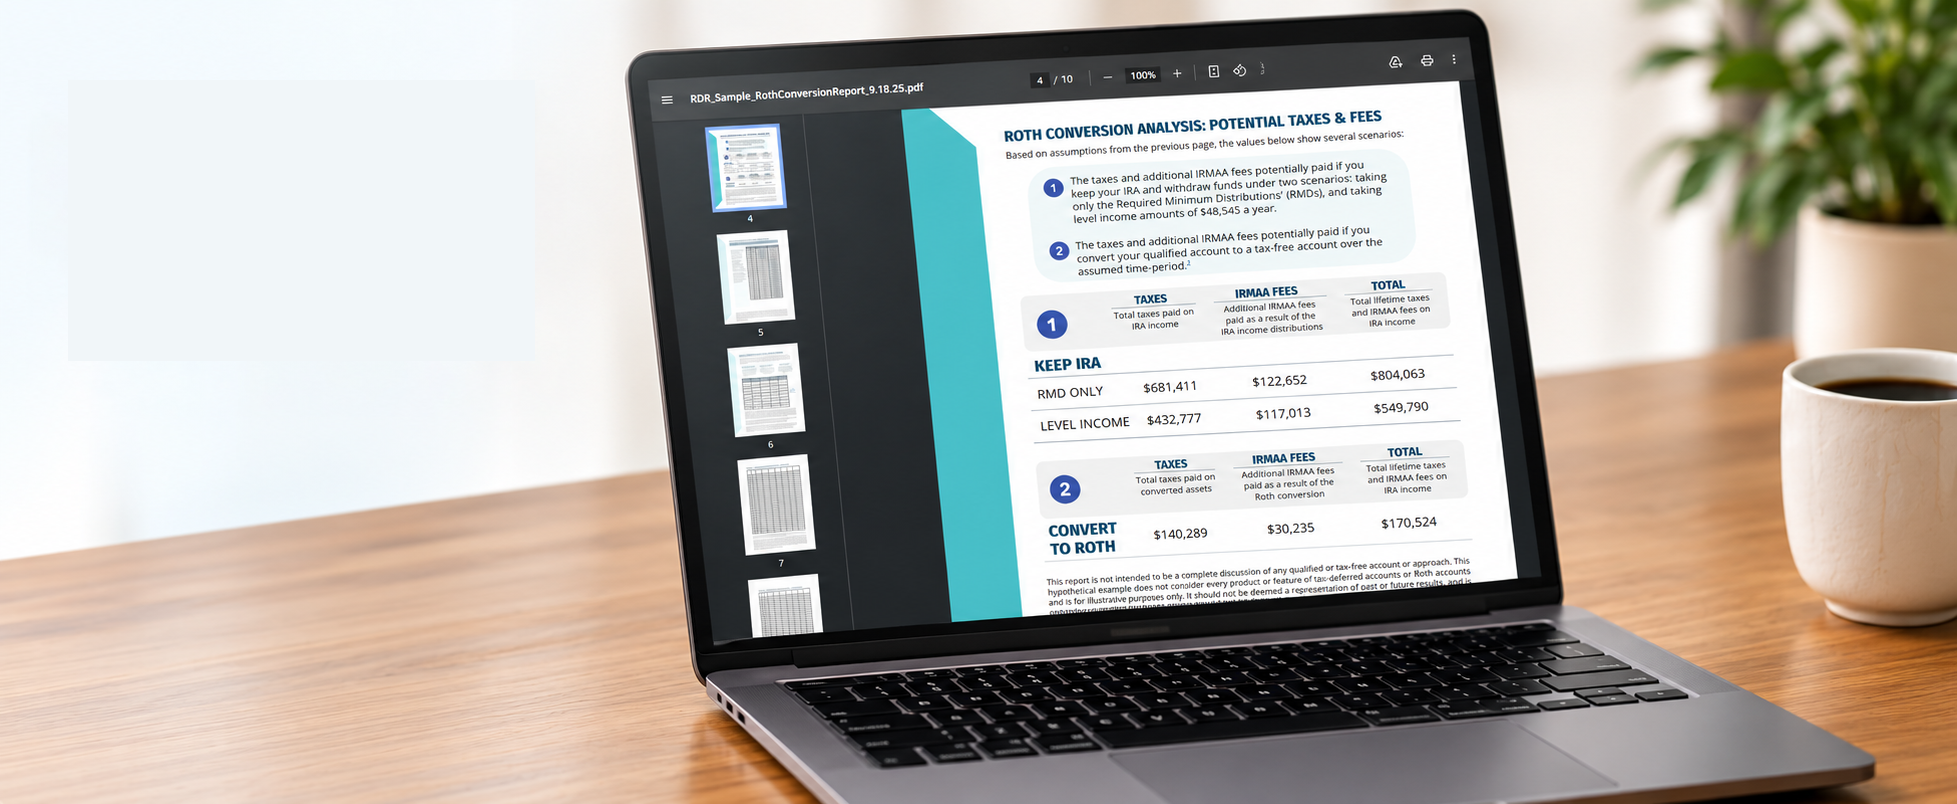
Tax analysis software has become more popular in recent years as advisors work to address this need. Platforms like Stonewood’s Roth Done Right software can quickly analyze taxes, IRMAA and deductions to help you structure optimal Roth conversions strategies fast. You can even leverage bonus annuities and life insurance into the analysis.
The key is to incorporate a client-friendly tax analysis into your retirement income and legacy conversations, making sure you’re offering real insight – and real solutions – around reducing taxes in retirement.
Strategy 2: Set a contact rhythm clients can count on
When it comes to connecting with clients, how often is often enough?
Savers have an answer. In a 2024 YCharts survey, 79% of savers wanted contact at least every three months – yet 37% said they heard from their financial advisor rarely or not often [3].
The stakes rise with wealth. Among clients with $500,000 or more under advice, 88% said more contact would sway their decision to keep the advisor, and 89% said it would affect whether they recommend the advisor [3].
Kitces Research found a similar pattern on the advisor side. Teams with an average revenue under $5,000 per client had a median of 14 client touchpoints a year. Teams at $12,500 or more had a median of 20 client touchpoints a year [8].
Sticking with the topic of taxes, the yearly calendar can offer a natural rhythm. Here’s one example of a quarterly outreach on taxes:
Quarter
Engagement topic
Q1 (January to March)
Tax season check-in: new brackets, new deductions, IRMAA notices
Q2 (April to June)
Annual review and goal update
Q3 (July to September)
Midyear income check: are we on track for this year’s tax picture?
Strategy 3: Turn the annual review into a tax review
Most annual reviews start by looking backward: how did the accounts do over the previous year? But the real power of the annual review is in looking forward: What decisions are coming? What might change, and how do we minimize costs while maximizing benefits? Are there new funds, or new planning opportunities available?
If you’re looking for topics that open planning opportunities at your annual reviews, the three below will power planning from 2026 through 2027:
IRMAA. Many savers don’t know about the Medicare surcharge for higher-income earners until they’ll hit with it. That makes IRMAA a great conversation opening for Roth conversions and other tax-free strategies that can minimize both future taxes and future IRMAA fees.
An IRMAA analysis can be eye-opening for your clients. By analyzing potential lifetime IRMAA fees for your clients in their current strategy versus a reallocated tax-free strategy, you can open real planning conversations around tax mitigation. Today’s Roth analysis software makes it easy. Stonewood’s Roth Done Right software calculates the best structures to reduce IRMAA fees during a Roth conversion – and even outputs a total IRMAA paid versus total IRMAA saved for the lifetime of the client.
The senior deduction. The new senior deduction – passed as part of OBBBA in an effort to offset the taxes seniors pay on their Social Security benefits – is a great topic for annual reviews.
Savers age 65 and older may claim an extra $6,000 deduction ($12,000 if both spouses qualify) for tax years 2025 through 2028. It phases out above $75,000 of modified adjusted gross income for single filers and $150,000 for joint filers [11].
Because the deduction is both new and temporary, many clients are interested to hear their specifics. Our post on OBBBA tax changes article covers the details.
RMDs. Required minimum distributions start at age 73 for people born 1951 to 1959 and at age 75 for those born in 1960 or later [12]. The years before RMDs can be a window to manage future taxable income. Our Roth conversion rules for 2026 explain the mechanics.
A reminder that it’s important to judge each Roth conversion decision on the metric that matters most to your client. For many savers, that’s reducing lifetime taxes and maximizing lifetime after-tax wealth. Our post on Roth conversion break-even walks through how to analyze and frame Roth strategies for your clients.
Free Advisor Training
Turn Roth Conversations Into Revenue
Watch this complimentary training to learn how leading advisors use retirement tax concerns to create urgency, open Roth conversion conversations, and uncover valuable new planning opportunities.
Video Training
Create urgency around tax planning
Open more Roth conversion conversations
Uncover new planning opportunities
Strategy 4: Show the numbers on one page
Clients engage with what they can see and understand. Many advisors find that the incredible 40-page plan they’ve developed just sits in a client’s drawer, offering information that’s too much or too confusing for the client to act on.
The analysis you show your clients should drive decision-making behavior. And one way to do that is to focus on the numbers that matter most to your clients.
A quick snapshot of taxes paid vs. taxes saved will open more client conversations than a 40-page analysis ever will. Take Stonewood’s Total Tax Burden report, for example. In under 60 seconds (and with no tax return needed) it can show your clients their potential retirement tax bill if they stay on their current path – and their potential tax savings through doing some planning with you.
Strategy 5: Teach in groups with webinars and books
Education builds trust before a client ever sits in your office. Successful offices educate their clients throughout the year, achieving two goals at once: First, education reinforces the strategies you’ve already put in place, and reminds clients why they hired you in the first place. Second, education opens new planning opportunities for new assets in new areas.
For example, a webinar on retirement taxes might help Client A feel good about the Roth conversion they started last year. The same webinar might make Client B realize they need a better approach to taxes in retirement, and open a conversation about Roth conversions.
Books play well into this educational space, too.
Print books are one of the most undervalued educational tools independent financial advisors can use. First, a book is a gift; it’s something you give a client that’s theirs to enjoy and keep. Second, books serve as third-party validation to the strategies you’re recommending.
One of the most popular retirement tax books in the industry today is The Road Less Taxed, which is a lighthearted and enjoyable journey through what’s happening in Washington, how it could impact your client’s retirement approach, and what they can do to prepare today. You can request a free copy of the book here.
Strategy 6: Earn referrals by giving something of value
Referrals are the clearest sign of engagement. In the 2026 Kitces marketing study, the typical practice got 62% of its new clients from client referrals, and 88% of practices used them. Client referrals had a RAC of $0.34, about half the median for all channels [4].
Surprisingly, the same study also found that asking for referrals appears to reduce referral volume [4]. And that’s because many independent advisors aren’t asking for referrals in an optimal way.
The key to a successful referral ask? Give first.
Rather than simply asking clients for a name, give them something of value to deliver to their friends and family: an invitation to a special webinar or event, a book, or a personal estimate of a friend’s potential retirement tax bill. A gift delivers value first and leads to more referrals overall.
Strategy 7: Bring the spouse and the heirs into the room
Cerulli expects $124 trillion to transfer through 2048. And the sad truth is, many advisors don’t keep that money.
In Cerulli’s 2025 research, only 27% of affluent people expecting an inheritance said they’d keep their benefactor’s advisor. Among those who had already inherited, only 20% did [5]. And in J.D. Power’s 2026 study, only 39% of clients 40 and older said their advisor had discussed a future wealth transfer with them [15].
Engagement with the next generation of your client’s money is critical. And legacy planning is a great way to start the conversation. Tools like Stonewood’s Legacy Done Right analysis can help start a family-wide conversation about minimizing taxes and maximizing wealth as it passes between generations.
You can’t improve what you don’t track. Pick a few measures and check them each quarter:
Review attendance: share of households that met with you this year.
Touchpoints per household: compare against your service tier.
Tax conversations held: share of households with a current tax analysis on file.
Referrals received: new clients who came from existing clients.
Event participation: clients who attended a seminar or webinar or brought a guest.
Retention: households lost, and the reason given.
Next-generation contact: households where you’ve met the spouse and at least one heir.
Your CRM can track many of these. If you’re comparing tools, our guide to financial advisor software ranks the main options by category.
Common mistakes to avoid
Contact without content. A “just checking in” email gives the client nothing to act on.
Reviews that only look back. Performance matters, but the next decision matters more.
Talking only to one spouse. Both spouses, and often the heirs, shape the relationship’s future.
Too much detail. Clients need the takeaway, not the spreadsheet.
FAQs
What are the best client engagement strategies for financial advisors?
Strategies backed by recent research include leading with tax planning, setting a regular contact rhythm (many clients want quarterly contact), turning annual reviews into forward-looking tax reviews, using simple one-page visuals, teaching through seminars and webinars, earning referrals by offering value, and building relationships with spouses and heirs.
How often should a financial advisor contact clients?
In the YCharts 2024 survey, 79% of clients wanted contact at least every three months [3]. Kitces Research found a median of 14 to 20 touchpoints a year, depending on service level [8]. A quarterly calendar tied to the tax year gives each contact a clear purpose.
Why do clients leave their financial advisor?
In a Morningstar study of people who had fired an advisor, the top reasons were the quality of advice and services (32%) and the quality of the relationship (21%). Cost was third at 17% [1].
How can advisors keep clients’ heirs after a wealth transfer?
Meet the heirs before the transfer. Cerulli found only 20% of affluent heirs who had inherited kept the benefactor’s advisor [5]. Showing heirs how the plan affects their own taxes, such as the 10-year rule on inherited IRAs, gives them a reason to stay.
Do educational seminars still work for financial advisors?
Kitces Research’s 2026 study found seminars cost about $1.76 per $1 of new revenue, and fast-growing firms were more likely to host in-person seminars [13]. Webinars were used by fewer firms in 2026 than in 2024 [4].
Should advisors ask clients for referrals?
The 2026 Kitces marketing study found that asking for referrals appears to reduce referral volume [4]. Many advisors get better results by giving clients something of value to share, such as a seminar invitation or a personal tax estimate.
See your clients’ potential tax bill
The strongest engagement strategy is a conversation about the client’s own numbers. When a client sees their potential retirement tax bill, maybe for the first time, the next meeting tends to book itself.
“Why Investors ‘Break Up’ With Financial Advisors,” Danielle Labotka, Morningstar, April 8, 2026. Accessed 10/13/26. Available online: https://www.morningstar.com/business/insights/blog/why-investors-break-up-with-their-financial-advisor
“2025 Social Security Survey,” Nationwide Retirement Institute, August 18, 2025 (fielded June 2 to July 10, 2025; n=1,812). Accessed 10/13/26. Available online: https://www.nationwide.com/financial-professionals/blog/retirement-savings-income/articles/social-security-misconceptions-retirement-readiness
“Advisor-Client Communication Survey 2024,” YCharts, February 2024 (n=775). Accessed 10/13/26. Available online: https://go.ycharts.com/hubfs/YCharts_Advisor_Client_Communication_Survey_2024.pdf
“How Financial Planners Actually Market Their Services,” The Kitces Report, 2026 Marketing Study, Kitces Research, September 2026 (n=506). Accessed 10/13/26. Available online: https://www.kitces.com/wp-content/uploads/2026/09/Kitces-Marketing-Survey-2026-3.pdf
“Many Investors Expect Inheritances, Yet Few Likely to Maintain Benefactor’s Advisor,” Cerulli Associates, September 3, 2025. Accessed 10/13/26. Available online: https://www.cerulli.com/press-releases/many-investors-expect-inheritances-yet-few-likely-to-maintain-benefactors-advisor
“Allianz Life Study Finds Fear of Running Out of Money Over Death at Record High,” Allianz Life, 2026 Annual Retirement Study, April 23, 2026. Accessed 10/13/26. Available online: https://www.businesswire.com/news/home/20260423084227/en/Allianz-Life-Study-Finds-Fear-Of-Running-Out-of-Money-Over-Death-At-Record-High
“Customized at Scale: A Framework for Next-Generation Advisory,” Cerulli Associates with Parametric, as reported by Family Wealth Report, October 3, 2025. Accessed 10/13/26. Available online: https://www.familywealthreport.com/printarticle.php?id=205752
“Financial Advisor Client Touchpoints, Revenue and Service Personalization,” Kitces Research, 2024. Accessed 10/13/26. Available online: https://www.kitces.com/blog/financial-advisor-client-touchpoints-revenue-service-personalization-roi-cost-strategies/
“2026 Medicare Parts A & B Premiums and Deductibles,” Centers for Medicare & Medicaid Services. Accessed 10/13/26. Available online: https://www.cms.gov/newsroom/fact-sheets/2026-medicare-parts-b-premiums-deductibles
“Premiums: Rules for Higher-Income Beneficiaries,” Social Security Administration. Accessed 10/13/26. Available online: https://www.ssa.gov/benefits/medicare/medicare-premiums.html
“Check Your Eligibility for the New Enhanced Deduction for Seniors,” Internal Revenue Service, February 27, 2026. Accessed 10/13/26. Available online: https://www.irs.gov/node/156821
“Retirement Plan and IRA Required Minimum Distributions FAQs,” Internal Revenue Service. Accessed 10/13/26. Available online: https://www.irs.gov/retirement-plans/retirement-plan-and-ira-required-minimum-distributions-faqs [VERIFY: confirm page states the age 75 tier for those born 1960 or later]
“Kitces Research Pegs the Winners and Losers in Marketing ROI,” Financial Planning, September 15, 2026. Accessed 10/13/26. Available online: https://www.financial-planning.com/news/kitces-research-pegs-the-winners-and-losers-in-marketing-roi
“Cerulli Anticipates $124 Trillion in Wealth Will Transfer Through 2048,” Cerulli Associates, December 5, 2024. Accessed 10/13/26. Available online: https://www.cerulli.com/press-releases/cerulli-anticipates-124-trillion-in-wealth-will-transfer-through-2048
J.D. Power 2026 U.S. Investor Satisfaction Study press release, March 18, 2026. Accessed 10/13/26. Available online: https://www.businesswire.com/news/home/20260318603550/en
This article is for educational purposes for financial professionals. Stonewood Financial is not a CPA firm and does not provide tax, legal or securities advice. Survey figures are as published by each source on the dates listed.
Free Study Group Replay
How Stonewood Advisors Stay Ahead of the Next Planning Conversation.
Watch a recent Stonewood Study Group focused on the legacy planning conversation. You’ll see how Stonewood helps advisors break down timely planning topics, client conversation angles, and practical strategies you can put to use immediately.
Expert insights. Real strategies.
Study Group Replay
Timely planning topics
Real client conversation angles
Practical strategies you can use
Real Advisors. Real Results.
See how advisors are using Stonewood software to win larger cases and deliver better
outcomes for their clients.
An advisor was working with a prospect who was a real "do-it-yourselfer" when it came to Roth conversions.
The client was converting assets up their existing tax bracket – and hadn't considered any impact to
IRMAA.
With Roth Done Right, the advisor was able to show an alternate pattern that sped up the conversion to
6 years. The new structure offered $30,000 savings in conversion taxes – a 20% reduction on the
prospect's conversion tax bill. The report also showed hundreds of thousands of dollars in long-term
tax and IRMAA savings from the converted assets – an amount the prospect hadn't been able to quantify
on his own.
Outcome
A new client with $1M in new AUM, and a $1M FIA sale to fund the conversion process.
An advisor was working with a prospect who already had assets with Ken Fisher. Fisher's team presented a
5% systematic withdrawal projection, so the advisor needed a stronger way to frame the income
conversation.
Using the Annuity Alpha report, the advisor showed how an annuity could deliver over 8% in annual cash
flow with lifetime income, plus a long-term care doubler. The contrast was clear enough that the prospect
moved forward.
Outcome
$1.5M placed and a $100K in new business revenue.
An advisor was working with a 58-year-old couple with an established, well-funded retirement income plan,
leaving an additional $3M IRA to build out a legacy for the kids. The couple's existing advisor had no
real additional plan for this money, other than to keep it in their managed account and grow that money as
much as possible for the kids.
Using the Legacy Done Right report, the advisor showed the need for tax planning on this $3M IRA.
According to the advisor, the simple analysis "opened up the wallet" to the Roth conversion story. The
advisor then used the blended Roth/Life feature in the report to show a blend of Roth Conversion assets
with some Life Insurance to help maximize the client’s legacy.
Outcome
$3M in motion. The advisor picked up a $1.5M FIA sale that will be converted to Roth. And the advisor
also sold a 5-Pay Protection focused IUL policy at $225,000 of premium per year.
An advisor group incorporated the Total Tax Burden report into the strategy presentation for all new
prospects. They ran the tax snapshot for every new client as part of their first meeting conversation,
quantifying the growing tax burden of IRA money – and illustrating the kinds of tax savings possible
when working with their firm.
Starting in January of 2023, this simple analysis was presented to every single prospect who walked in
the door. The goal was to differentiate their practice and drive overall revenue growth through various
Roth conversion strategies.
Outcome
From 2022 to 2025, new annual AUM rose from $5M to $50M. Annual FIA sales rose from $3M to $35M.
And annual life premium rose from $50K to $1M.
8 Ways to Turn a Book Into a Lead-Generation Machine
Discover how advisors can use books to warm up cold prospects, create more meaningful follow-up, boost event conversions, and open stronger retirement planning conversations.
Your guide is on its way
Check your inbox for 8 Ways to Turn a Book Into a Lead-Generation Machine. If it isn't there in a few minutes, look in your spam or promotions folder.
Turn books into conversations
Build trust before the first meeting
Create a stronger advisor follow-up system
Close More Business with Stonewood Reports
Easy to run. Easy to present. Pick the report that fits your next client conversation and we'll send a sample to your inbox immediately.
Pick a report. We'll email a sample instantly.
Roth Done RightTax & IRMAA Analysis
Annuity AlphaFIA vs. Managed Account
Legacy Done RightLife Insurance Analysis
Total Tax BurdenRetirement Tax Snapshot
Real insights Practical strategies Easy to present.