Every news item out of Washington seems to include details of a new or expanded tax. And generally, American savers have come to expect rising taxes in the years ahead. At your next seminar or workshop, ask the audience how many people think taxes are going up in the future; nearly everyone will raise their hands.
Yet while savers understand we’ve entered a rising tax environment, surprisingly few of them have used that knowledge to change how they save for retirement.
They continue to defer taxes on all or most of their retirement assets, seemingly failing to connect that higher taxes in the future means they’ll owe more in taxes on those funds and have less money set aside for retirement.
Close More Business with Stonewood Reports
Easy to run. Easy to present. Pick the report that fits your next client conversation and we'll send a sample to your inbox immediately.
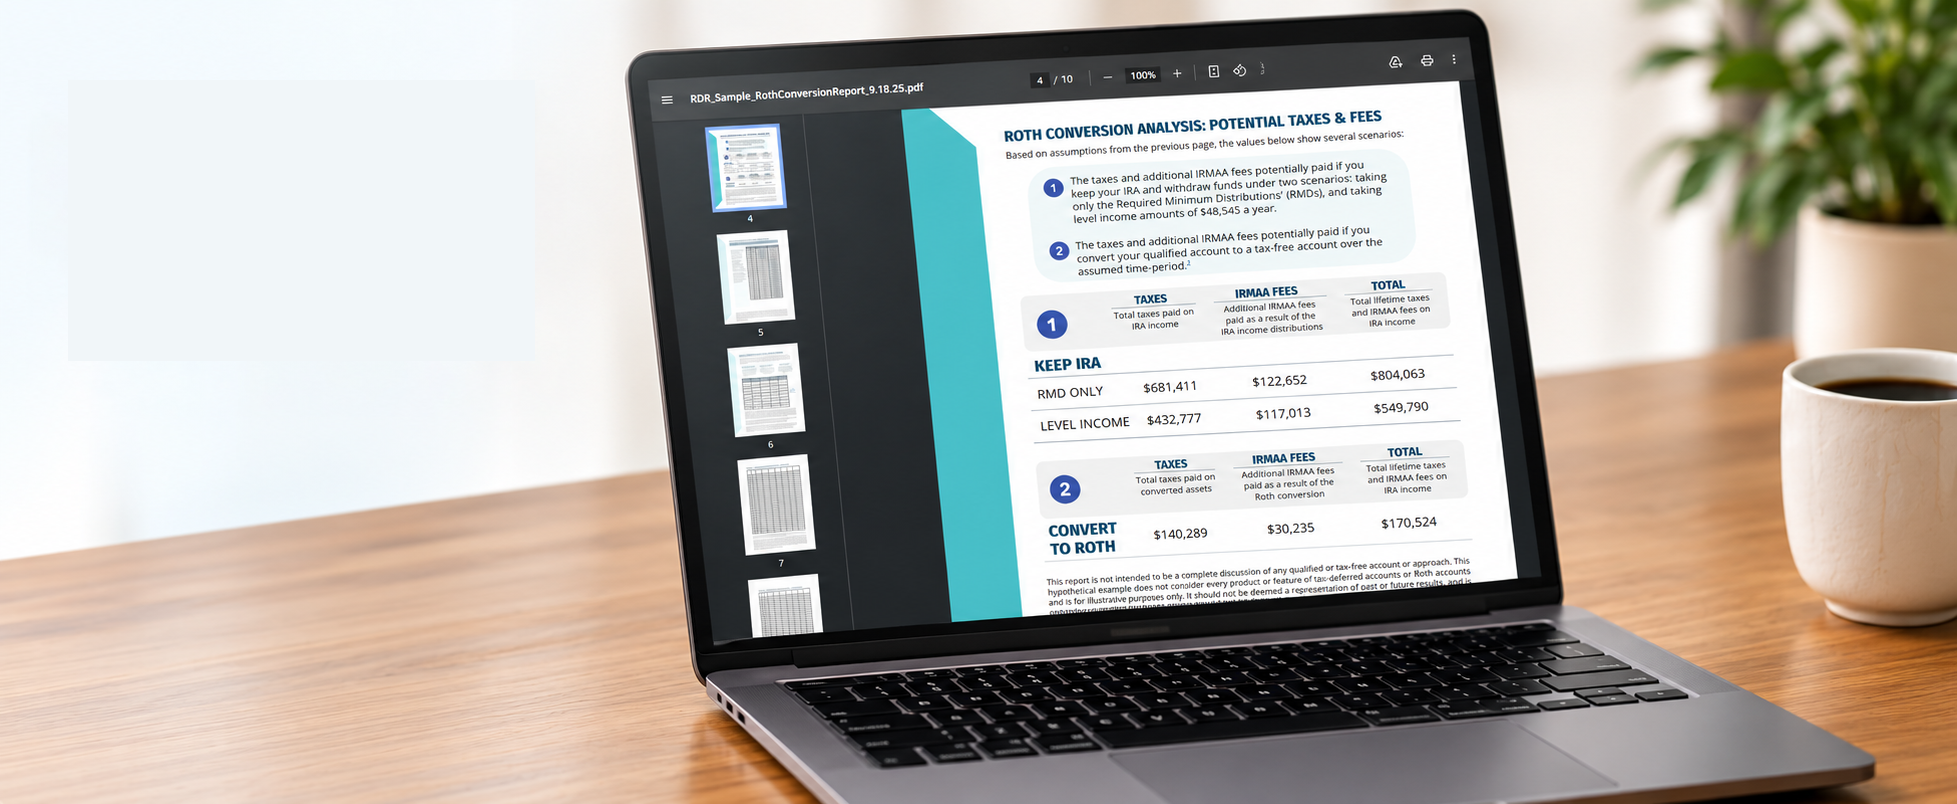
Roth Done RightTax & IRMAA Analysis
Annuity AlphaFIA vs. Managed Account
Legacy Done RightLife Insurance Analysis
Total Tax BurdenRetirement Tax Snapshot
So how can we, as advisors, help our clients overcome this disconnect?
The financial services industry is built to help clients face new risks. In fact, if you ask most advisors why their clients do business with them, part of that answer is: “I help my clients mitigate risk.” We help savers reduce uncertainty to make retirement more predictable and successful.
How do we do that? Simple. We use a process:
Identify the risk.
Quantify that risk.
Build a plan to mitigate that risk.
It started with the market. Savers wanted – and needed – the power of the stock market to grow their funds. It was a simple formula: Put money aside, invest it the stock market, and watch it grow. Until it didn’t. During market downturns, savers learned about risk. The advisor community learned to identify that risk by creating and using fancy terms like alpha and beta. The industry helped create tools like monte carlo simulations to quantify that risk for clients. Finally, advisors would use those tools to build asset allocation models to mitigate market risk.
This focus on accumulating wealth was the primary focus of our industry until a few things happened: the dot com bubble burst, followed shortly thereafter by the financial crisis. Suddenly, savers were reaching retirement age with depleted assets and no plan to generate income. And that problem was compounded by the reality that retirees were living longer than ever.
Advisors learned to Identify that Income Risk as Longevity Risk. Suddenly, it wasn’t enough to just accumulate funds; savers needed a plan to make those funds last a lifetime. This led to the boom in annuities and guaranteed income riders, the perfect solution to provide a guaranteed check clients couldn’t outlive. In the 2000s, advisors who became experts in income planning flourished. And shortly thereafter, most advisors across the industry were using annuities to offset income risk.
Today, the headlines are all about taxes. And advisors who understand Tax Risk today are the ones who will flourish as leaders in the next wave of the financial industry’s development.
We can apply the same financial planning process we used to address market and income risks: Help clients identify their tax risk, quantify it in dollars and cents, and then find tools to reduce that risk.
Stonewood can help do all three.
Our prospecting and marketing materials help you uncover the tax risk of your clients by changing the way you communicate the risks of retirement. Whether you’re hosting a seminar or workshop, talking to a TV or radio audience, or meeting with prospects one-on-one, we have tools to educate your audience on the risk of rising taxes – and why it’s critical to address that risk now.
Next, our client report software helps you quantify tax risk for your clients. Most people who sit across the desk from us have been programed to save in tax-deferred vehicles. It’s the default savings approach in America. So shake them up: Show them the cost of tax deferral by calculating their total taxes in retirement. Help them make educated decisions about the tax status of their retirement assets going forward. I promise, you’ll watch their jaws drop – and you’ll be thanked as the first advisor who’s helped them understand this pressing retirement risk.
And finally, Stonewood will train you on building client plans to mitigate the risk of rising taxes in retirement – particularly using the tax benefits of life insurance to offset tax risk.
The results for your clients? A complete retirement approach that addresses their complete retirement risks:
How Stonewood Advisors Stay Ahead of the Next Planning Conversation.
Watch a recent Stonewood Study Group focused on the legacy planning conversation. You’ll see how Stonewood helps advisors break down timely planning topics, client conversation angles, and practical strategies you can put to use immediately.
Strategy expertise and training that actually moves the needle. Neil sees the big opportunities coming - and develops tools to let you take advantage of them.
Real Advisors. Real Results.
See how advisors are using Stonewood software to win larger cases and deliver better
outcomes for their clients.
An advisor was working with a prospect who was a real "do-it-yourselfer" when it came to Roth conversions.
The client was converting assets up their existing tax bracket – and hadn't considered any impact to
IRMAA.
With Roth Done Right, the advisor was able to show an alternate pattern that sped up the conversion to
6 years. The new structure offered $30,000 savings in conversion taxes – a 20% reduction on the
prospect's conversion tax bill. The report also showed hundreds of thousands of dollars in long-term
tax and IRMAA savings from the converted assets – an amount the prospect hadn't been able to quantify
on his own.
Outcome
A new client with $1M in new AUM, and a $1M FIA sale to fund the conversion process.
An advisor was working with a prospect who already had assets with Ken Fisher. Fisher's team presented a
5% systematic withdrawal projection, so the advisor needed a stronger way to frame the income
conversation.
Using the Annuity Alpha report, the advisor showed how an annuity could deliver over 8% in annual cash
flow with lifetime income, plus a long-term care doubler. The contrast was clear enough that the prospect
moved forward.
Outcome
$1.5M placed and a $100K in new business revenue.
An advisor was working with a 58-year-old couple with an established, well-funded retirement income plan,
leaving an additional $3M IRA to build out a legacy for the kids. The couple's existing advisor had no
real additional plan for this money, other than to keep it in their managed account and grow that money as
much as possible for the kids.
Using the Legacy Done Right report, the advisor showed the need for tax planning on this $3M IRA.
According to the advisor, the simple analysis "opened up the wallet" to the Roth conversion story. The
advisor then used the blended Roth/Life feature in the report to show a blend of Roth Conversion assets
with some Life Insurance to help maximize the client’s legacy.
Outcome
$3M in motion. The advisor picked up a $1.5M FIA sale that will be converted to Roth. And the advisor
also sold a 5-Pay Protection focused IUL policy at $225,000 of premium per year.
An advisor group incorporated the Total Tax Burden report into the strategy presentation for all new
prospects. They ran the tax snapshot for every new client as part of their first meeting conversation,
quantifying the growing tax burden of IRA money – and illustrating the kinds of tax savings possible
when working with their firm.
Starting in January of 2023, this simple analysis was presented to every single prospect who walked in
the door. The goal was to differentiate their practice and drive overall revenue growth through various
Roth conversion strategies.
Outcome
From 2022 to 2025, new annual AUM rose from $5M to $50M. Annual FIA sales rose from $3M to $35M.
And annual life premium rose from $50K to $1M.