If you’ve turned on the news lately (or read the paper… or looked at social media… or talked to practically anyone), you’re undoubtedly aware we’re a year away from the 2024 Presidential election.
And what an election it’s shaping up to be!
Like the last several election cycles, this one will be heated, and focused on both domestic and international issues. Taxes, spending, and foreign aid are sure to be in the mix.
But what does it all mean for our clients?
It’s an unsettling truth: The debate in Washington can have a big impact on the success – or failure – of your client’s retirement approach.
As financial advisors, it’s our responsibility to evaluate the election and its potential impact on the savings approaches our clients use for their retirement funds.
What’s more, we need to consider both the immediate and long-term impact.
I know what you’re thinking: “That sounds like a lot of work!”
But I’m here to share a little secret with you: Helping your clients identify and mitigate the risks coming from Washington is actually much easier than you think.
Addressing Legislative Risk
In my past life, I was a Washington insider.
I started my career in the nation’s capital, working in the White House and on Capitol Hill. And my time in the swamp helped me understand the decisions made in Washington can have a direct impact on the savings of millions of Americans – your clients included.
My time in Washington also helped me realize it isn’t difficult to help your clients protect themselves from legislative risks… IF you understand them (and leverage some fundamentals of financial planning you’re probably already using in your practice).
It’s become my passion to help advisors like you understand, quantify, and mitigate Tax Risk and Legislative Risk for your clients.
So if you’re feeling lost or concerned, here are three of my favorite resources that can help:
First things first, let’s define Tax Risk and Legislative Risk. Here’s a quick primer I put together on the difference and why successful retirement approaches should address them both.
I just hosted a webinar on how the current debate in Washington could impact your clients – and what you can do about it.Check out the recording here. In a focused 20 minutes, I cover everything from the debt and federal spending to tax policy and pending legislation.
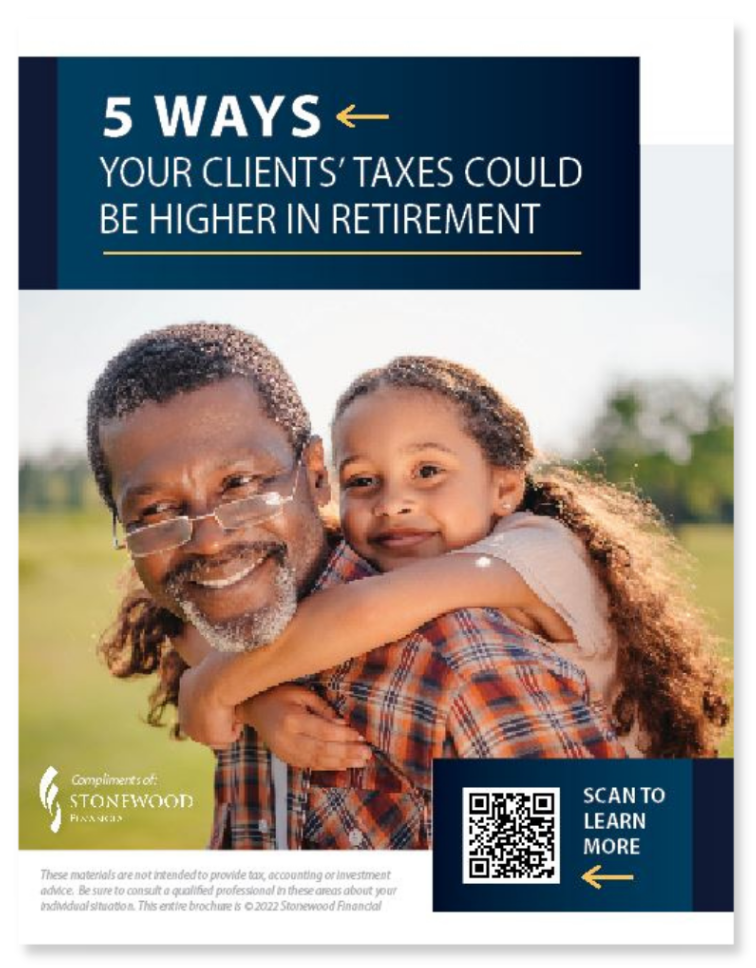
This is one of my favorite pieces of content we’ve published here at Stonewood Financial. In this brochure, I cover five ways your client’s taxes could be higher in retirement based on what’s happening in Washington today – and, of course, how to help them reallocate assets to protect against the risk of rising taxes.
{{cta(’18c8ddbc-3d4a-46a5-a4c0-4ae56a662088′)}}
In the financial services industry, we talk a lot about offering holistic services to our clients.
But for me, an advisor isn’t truly holistic unless they are actively helping their clients mitigate tax and legislative risk in retirement.
Because the 2024 elections are coming, and then the 2026 elections, the 2028 elections, the….
You get my point. Every two years, our country elects new government, new leaders, and the potential for new taxes, new spending, and new regulations.
It’s your job to help your clients prepare. And here at Stonewood Financial, it’s our job to make it easy for you to do so.
And know that no matter what the 2024 election brings, it doesn’t have to be doom and gloom for your clients.
Free Study Group Replay
How Stonewood Advisors Stay Ahead of the Next Planning Conversation.
Watch a recent Stonewood Study Group focused on the legacy planning conversation. You’ll see how Stonewood helps advisors break down timely planning topics, client conversation angles, and practical strategies you can put to use immediately.
Expert insights. Real strategies.
Study Group Replay
Timely planning topics
Real client conversation angles
Practical strategies you can use
Real Advisors. Real Results.
See how advisors are using Stonewood software to win larger cases and deliver better
outcomes for their clients.
An advisor was working with a prospect who was a real "do-it-yourselfer" when it came to Roth conversions.
The client was converting assets up their existing tax bracket – and hadn't considered any impact to
IRMAA.
With Roth Done Right, the advisor was able to show an alternate pattern that sped up the conversion to
6 years. The new structure offered $30,000 savings in conversion taxes – a 20% reduction on the
prospect's conversion tax bill. The report also showed hundreds of thousands of dollars in long-term
tax and IRMAA savings from the converted assets – an amount the prospect hadn't been able to quantify
on his own.
Outcome
A new client with $1M in new AUM, and a $1M FIA sale to fund the conversion process.
An advisor was working with a prospect who already had assets with Ken Fisher. Fisher's team presented a
5% systematic withdrawal projection, so the advisor needed a stronger way to frame the income
conversation.
Using the Annuity Alpha report, the advisor showed how an annuity could deliver over 8% in annual cash
flow with lifetime income, plus a long-term care doubler. The contrast was clear enough that the prospect
moved forward.
Outcome
$1.5M placed and a $100K in new business revenue.
An advisor was working with a 58-year-old couple with an established, well-funded retirement income plan,
leaving an additional $3M IRA to build out a legacy for the kids. The couple's existing advisor had no
real additional plan for this money, other than to keep it in their managed account and grow that money as
much as possible for the kids.
Using the Legacy Done Right report, the advisor showed the need for tax planning on this $3M IRA.
According to the advisor, the simple analysis "opened up the wallet" to the Roth conversion story. The
advisor then used the blended Roth/Life feature in the report to show a blend of Roth Conversion assets
with some Life Insurance to help maximize the client’s legacy.
Outcome
$3M in motion. The advisor picked up a $1.5M FIA sale that will be converted to Roth. And the advisor
also sold a 5-Pay Protection focused IUL policy at $225,000 of premium per year.
An advisor group incorporated the Total Tax Burden report into the strategy presentation for all new
prospects. They ran the tax snapshot for every new client as part of their first meeting conversation,
quantifying the growing tax burden of IRA money – and illustrating the kinds of tax savings possible
when working with their firm.
Starting in January of 2023, this simple analysis was presented to every single prospect who walked in
the door. The goal was to differentiate their practice and drive overall revenue growth through various
Roth conversion strategies.
Outcome
From 2022 to 2025, new annual AUM rose from $5M to $50M. Annual FIA sales rose from $3M to $35M.
And annual life premium rose from $50K to $1M.