Most retirees learn about provisional income the same way: they get their first Social Security check, do their taxes the following April, and find out if a chunk of that check is taxable. It can be a surprise for many retirees – especially if their financial advisor hasn’t prepared them for the possibility.
Here’s the good news: Provisional income is mechanical. It’s a specific formula with specific inputs, and once you understand how it’s built, you can plan around it. The 2026 rules are exactly the same as the 2025 rules – . OBBBA did not change this formula. The Tax Cuts and Jobs Act did not change this formula. In fact, it’s one of the more stable pieces of the retirement tax code.
Let me walk you through the exact formula, the inputs that go in, the ones that don’t, and some examples at different income levels so you can see how it plays out.
Close More Business with Stonewood Reports
Easy to run. Easy to present. Pick the report that fits your next client conversation and we'll send a sample to your inbox immediately.
The IRS calls this “combined income” in Publication 915. Most advisors and planners call it “provisional income.” Here’s the general formula:
Provisional income = Adjusted gross income (AGI) + Tax-exempt interest + 50% of total Social Security benefits
That result is what the IRS compares to the two thresholds to decide how much of your Social Security becomes taxable. One important note: the 50% of Social Security that goes into the provisional income formula is not the same as the amount that ends up taxable. They’re two different numbers. The 50% figure is an input to the calculation. The actual taxable portion is the output.
2026 thresholds
Single, head of household, or qualifying surviving spouse: 50% taxable above $25,000; 85% taxable above $34,000
Married filing separately (lived with spouse any time during year): 85% taxable on any positive provisional income
That last one is worth pausing on. Married couples who file separately and who lived together at any point during the year face the 85% taxation rate on any positive provisional income. The thresholds effectively drop to zero. This is one of the few situations where filing jointly is almost always better for retirees, even when other factors might favor separate filing.
What counts as AGI for the calculation
Adjusted gross income is the total from line 11 of IRS Form 1040. For retirees, it typically includes:
Traditional IRA and 401(k) withdrawals, including RMDs
Pension and annuity income
Wages, self-employment income, and 1099 contract work
Dividends from taxable brokerage accounts
Interest from taxable accounts
Capital gains from taxable brokerage accounts, including short-term and long-term
Rental property net income
Royalties
Notice that this is AGI, not taxable income. The standard deduction, the senior bonus deduction from OBBBA, and itemized deductions all reduce taxable income but they do not reduce provisional income. That’s a common misunderstanding that trips up even experienced retirees.
Free Retirement Tax Guide
Free Advisor Training
Turn Roth Conversations Into Revenue
Watch this complimentary training to learn how leading advisors use retirement tax concerns to create urgency, open Roth conversion conversations, and uncover valuable new planning opportunities.
Video Training
Create urgency around tax planning
Open more Roth conversion conversations
Uncover new planning opportunities
The 5 Retirement Tax Surprises Your Prospects Won't See Coming
Download 5 Ways Taxes Can Rise in Retirement and uncover the often-overlooked tax risks that can reduce retirement income. It's a simple, powerful resource for starting more meaningful tax conversations with prospects and clients.
Get Your Free Copy
What doesn’t count in AGI (and why it matters)
A short list of retirement income sources that stay out of AGI and therefore don’t push up provisional income:
Qualified Roth IRA withdrawals (distributions of contributions and qualified distributions of earnings)
Roth 401(k) qualified distributions
Proceeds from health savings account withdrawals used for qualified medical expenses
Loans taken from permanent life insurance cash value (if structured as loans, not distributions)
Return of basis from non-qualified annuities (the exclusion ratio portion)
Gifts and inheritances received
This list is where a lot of retirement tax planning gets done. A retiree who has a meaningful Roth balance has income that simply doesn’t show up in the provisional income calculation. That’s the mechanical reason Roth conversions during low-income years can be so valuable for high-Social Security retirees: converted dollars become future withdrawals that are invisible to this formula.
The tax-exempt interest trap
Here’s the part that catches municipal bond holders by surprise. Tax-exempt interest, which is federally tax-free for ordinary income tax purposes, does count as an input to the provisional income formula. Municipal bond interest doesn’t appear in AGI, but it gets added right back in on the provisional income calculation.
The practical result is that a retiree holding a large municipal bond portfolio can still trigger Social Security taxation even though they’re technically collecting tax-free interest. For savers who loaded up on muni bonds specifically to avoid federal tax in retirement, this is a rude surprise. The bonds are doing their primary job, but they’re still reaching into the Social Security taxation calculation through a side door.
Three worked examples at different income levels
Let’s run some general math for three hypothetical retired couples, all age 68, with different income pictures. All figures use 2026 rules.
Example 1: Below the first threshold
Hypothetical Couple A: Combined Social Security $36,000, traditional IRA withdrawal $8,000, no other income.
AGI = $8,000
Tax-exempt interest = $0
50% of Social Security = $18,000
Provisional income = $8,000 + $0 + $18,000 = $26,000
The joint threshold for the first tier is $32,000. Provisional income of $26,000 is below it. Zero percent of Social Security is federally taxable. Couple A pays federal tax on the $8,000 IRA withdrawal only.
Example 2: Between the two thresholds
Hypothetical Couple B: Combined Social Security $42,000, traditional IRA withdrawal $15,000, pension $6,000.
AGI = $21,000
Tax-exempt interest = $0
50% of Social Security = $21,000
Provisional income = $21,000 + $0 + $21,000 = $42,000
This lands between $32,000 (first tier) and $44,000 (second tier). The taxable portion is calculated as the lesser of 50% of the excess over $32,000, or 50% of Social Security. That’s 50% x ($42,000 – $32,000) = $5,000 of Social Security becomes taxable. Couple B pays federal tax on $21,000 + $5,000 = $26,000 of ordinary income before deductions.
Example 3: Above the second threshold
Couple C: Combined Social Security $48,000, traditional IRA withdrawal $35,000, pension $18,000, tax-exempt municipal interest $5,000.
Provisional income = $53,000 + $5,000 + $24,000 = $82,000
This is well above the $44,000 second-tier threshold. The taxable portion is the lesser of 85% of Social Security ($40,800) or the sum of 85% of the excess above $44,000 plus the amount taxable under the first-tier formula. Working it out, roughly $40,800 of Social Security becomes taxable. Couple C’s AGI-based ordinary income for tax purposes is $53,000 + $40,800 = $93,800 before deductions. Their $5,000 of muni interest stays out of ordinary tax, but it contributed to getting 85% of their Social Security pulled into the taxable pile.
How the 2026 OBBBA senior bonus deduction interacts
OBBBA added a new age-65+ deduction of $6,000 for single filers and $12,000 for married filing jointly, with phase-outs starting at roughly $77,000 single and $155,000 joint AGI for 2026 (IRS, 2026 inflation release). This deduction reduces taxable income but does not reduce AGI. Because the provisional income formula starts with AGI, the senior bonus deduction has zero effect on how much of your Social Security gets pulled into taxation.
In practice, the senior deduction shaves the final tax bill by reducing the income the brackets are applied to, but it does not change the provisional income calculation. It’s a real benefit, just not the right tool for Social Security taxation planning.
Three mechanical moves that reduce provisional income
1. Qualified Charitable Distributions after age 70.5
A QCD is a direct transfer from a traditional IRA to a qualified charity. The 2026 QCD limit is $111,000 per person per year (IRS, SECURE 2.0 inflation-adjusted). A QCD counts toward your RMD for the year but the amount never enters AGI. For retirees who give to charity anyway, redirecting RMDs through QCDs is the most efficient way to lower provisional income. Every dollar that goes through a QCD is a dollar that doesn’t land in the AGI side of the formula.
2. Shift assets from taxable to Roth before RMD age
Traditional-to-Roth conversions done in low-income years replace future AGI-generating withdrawals with invisible-to-the-formula Roth withdrawals. A retiree who converts $500,000 from traditional to Roth over a decade reduces the base of future RMDs, which is the biggest driver of retirement AGI. Smaller AGI means smaller provisional income.
3. Reconsider muni bonds if Social Security taxation is the concern
Municipal bonds are excellent at avoiding federal ordinary income tax on the interest itself. They’re not as effective at avoiding Social Security taxation because the interest still counts in provisional income. For retirees whose main tax concern is Social Security, a portfolio of Treasuries with a Roth conversion strategy may deliver better after-tax results than a large muni allocation. The right answer depends on numbers and client preferences , not blanket rules.
Common provisional income calculation mistakes
Here are some common calculation errors on provisional income to avoid:
Mistake 1: Using taxable income instead of AGI
The formula starts with AGI, not taxable income. Confusing the two is the single most common error. AGI is line 11 on Form 1040. Taxable income, the number after the standard deduction and any itemized deductions, is line 15. The provisional income formula uses the line 11 number. Every tool that uses line 15 here is wrong, and there are more of those than you’d expect.
Mistake 2: Forgetting to add back tax-exempt interest
Muni bond interest sits on line 2a of Form 1040. It stays out of regular AGI and regular taxable income. But it gets added right back in for provisional income. Skipping this step understates provisional income and can send a client into the torpedo zone they thought they were safely outside of.
Mistake 3: Using the full Social Security amount instead of 50%
The formula uses 50% of the total Social Security benefit, not the full amount. Doubling this input roughly doubles the provisional income number and often leads to recommendations for unnecessary withdrawal restrictions. Check the multiplier every time.
Mistake 4: Assuming the deduction reduces the formula
Both the standard deduction and the OBBBA senior bonus deduction reduce taxable income. Neither reduces AGI. Planners who subtract these from AGI before running provisional income produce artificially low numbers and miss torpedo exposures that will show up at tax time.
What advisors should build into planning software
Any retirement planning tool worth using should recalculate provisional income in every year of the projection, adjust the taxable portion of Social Security accordingly, and show the effective marginal tax rate on incremental income.
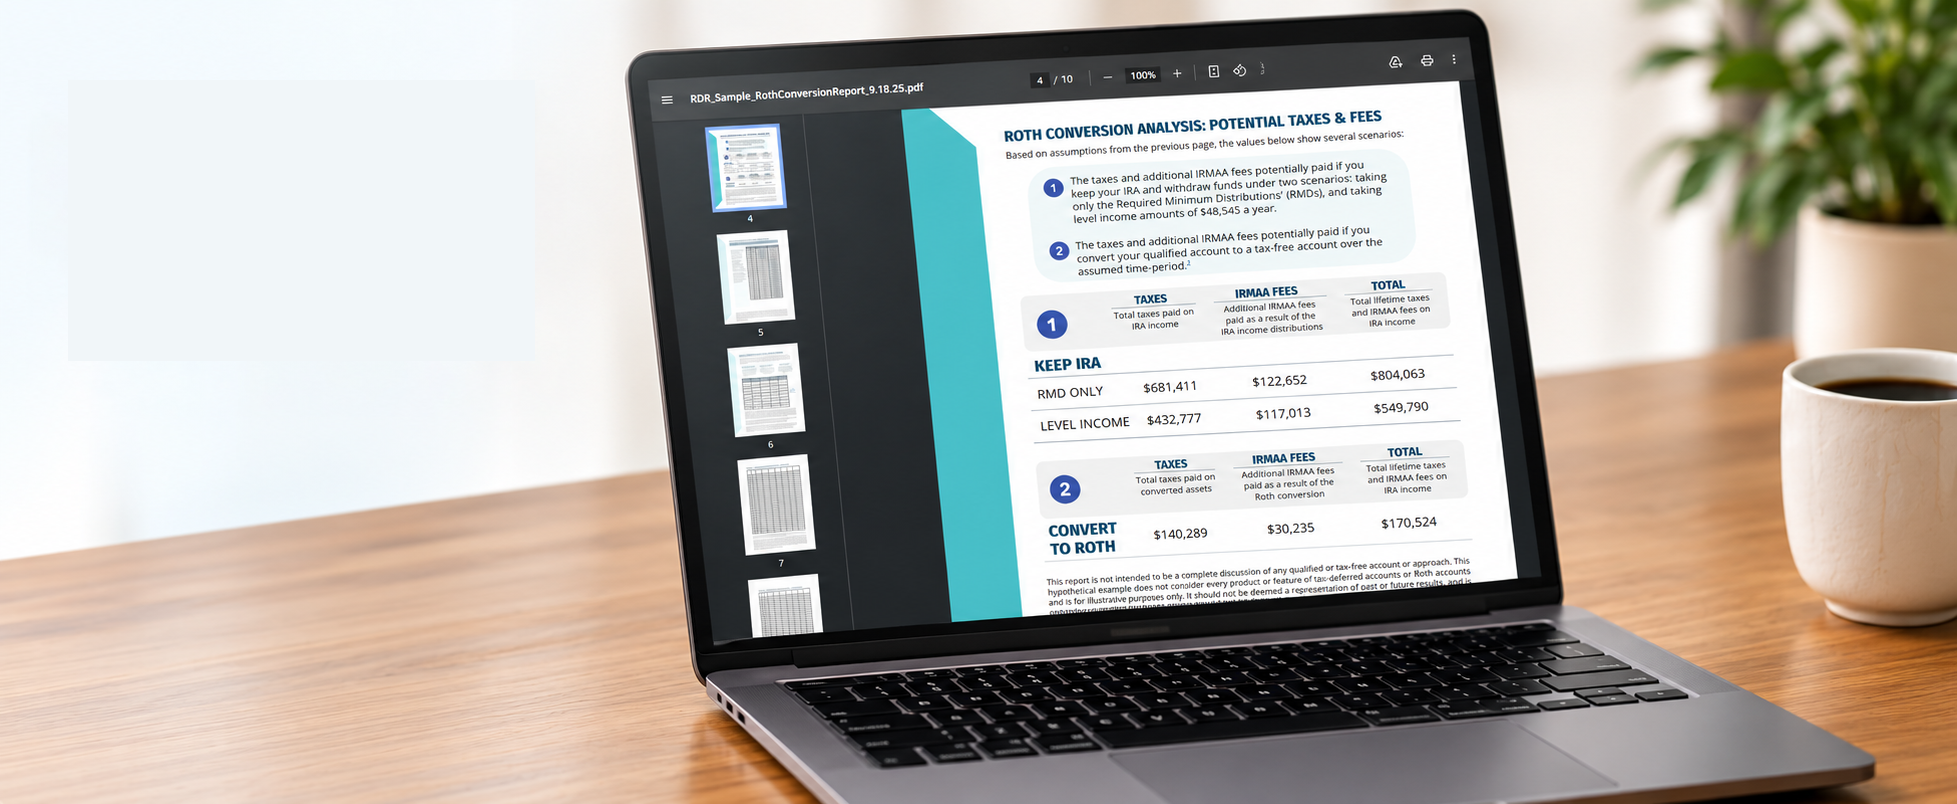
At Stonewood, this calculation runs in the background of every Roth Done Right scenario. Advisors can see year-by-year how provisional income changes based on conversion timing, and withdrawal sequencing. This can give clients a clearer overall picture of their strategy and approach.
This article does not constitute tax, legal, or financial planning advice. Consult a qualified professional before making decisions about your specific situation.
Frequently Asked Questions
What is provisional income?
Provisional income is the IRS formula used to decide how much of your Social Security benefit is federally taxable. It equals AGI plus tax-exempt interest plus 50% of your Social Security benefits.
What are the 2026 provisional income thresholds?
Single filers face 50% taxation of Social Security above $25,000 and 85% above $34,000. Married filing jointly thresholds are $32,000 and $44,000. These numbers have not been updated for inflation since 1993.
Does municipal bond interest count in provisional income?
Yes. Tax-exempt interest, including municipal bond interest, is added back into provisional income even though it’s excluded from regular AGI. This catches many retirees by surprise.
Do Roth IRA withdrawals count in provisional income?
Qualified Roth IRA withdrawals do not count in AGI and therefore do not count in provisional income. This is the mechanical reason Roth assets are valuable for retirees whose Social Security is at risk of heavy taxation.
Does the OBBBA senior bonus deduction lower provisional income?
No. The senior bonus deduction reduces taxable income but not AGI. Since provisional income is calculated from AGI, the senior deduction has no effect on how much Social Security becomes taxable.
How can I reduce my provisional income?
Use Qualified Charitable Distributions after age 70.5, shift assets from traditional to Roth in low-income years, and review whether a muni-heavy portfolio is the right fit if Social Security taxation is your main tax concern.
Free Study Group Replay
How Stonewood Advisors Stay Ahead of the Next Planning Conversation.
Watch a recent Stonewood Study Group focused on the legacy planning conversation. You’ll see how Stonewood helps advisors break down timely planning topics, client conversation angles, and practical strategies you can put to use immediately.
Strategy expertise and training that actually moves the needle. Neil sees the big opportunities coming - and develops tools to let you take advantage of them.
Real Advisors. Real Results.
See how advisors are using Stonewood software to win larger cases and deliver better
outcomes for their clients.
An advisor was working with a prospect who was a real "do-it-yourselfer" when it came to Roth conversions.
The client was converting assets up their existing tax bracket – and hadn't considered any impact to
IRMAA.
With Roth Done Right, the advisor was able to show an alternate pattern that sped up the conversion to
6 years. The new structure offered $30,000 savings in conversion taxes – a 20% reduction on the
prospect's conversion tax bill. The report also showed hundreds of thousands of dollars in long-term
tax and IRMAA savings from the converted assets – an amount the prospect hadn't been able to quantify
on his own.
Outcome
A new client with $1M in new AUM, and a $1M FIA sale to fund the conversion process.
An advisor was working with a prospect who already had assets with Ken Fisher. Fisher's team presented a
5% systematic withdrawal projection, so the advisor needed a stronger way to frame the income
conversation.
Using the Annuity Alpha report, the advisor showed how an annuity could deliver over 8% in annual cash
flow with lifetime income, plus a long-term care doubler. The contrast was clear enough that the prospect
moved forward.
Outcome
$1.5M placed and a $100K in new business revenue.
An advisor was working with a 58-year-old couple with an established, well-funded retirement income plan,
leaving an additional $3M IRA to build out a legacy for the kids. The couple's existing advisor had no
real additional plan for this money, other than to keep it in their managed account and grow that money as
much as possible for the kids.
Using the Legacy Done Right report, the advisor showed the need for tax planning on this $3M IRA.
According to the advisor, the simple analysis "opened up the wallet" to the Roth conversion story. The
advisor then used the blended Roth/Life feature in the report to show a blend of Roth Conversion assets
with some Life Insurance to help maximize the client’s legacy.
Outcome
$3M in motion. The advisor picked up a $1.5M FIA sale that will be converted to Roth. And the advisor
also sold a 5-Pay Protection focused IUL policy at $225,000 of premium per year.
An advisor group incorporated the Total Tax Burden report into the strategy presentation for all new
prospects. They ran the tax snapshot for every new client as part of their first meeting conversation,
quantifying the growing tax burden of IRA money – and illustrating the kinds of tax savings possible
when working with their firm.
Starting in January of 2023, this simple analysis was presented to every single prospect who walked in
the door. The goal was to differentiate their practice and drive overall revenue growth through various
Roth conversion strategies.
Outcome
From 2022 to 2025, new annual AUM rose from $5M to $50M. Annual FIA sales rose from $3M to $35M.
And annual life premium rose from $50K to $1M.