If you’ve ever heard me speak or attended one of Stonewood Financial’s Innovate trainings, you’ve undoubtedly heard me share some of my favorite conversation frames around taxes in retirement.
Message frames are incredibly useful in marketing for financial advisors. They can be molded to fit a seminar room with 100 people or a client meeting with 2.
Close More Business with Stonewood Reports
Easy to run. Easy to present. Pick the report that fits your next client conversation and we'll send a sample to your inbox immediately.
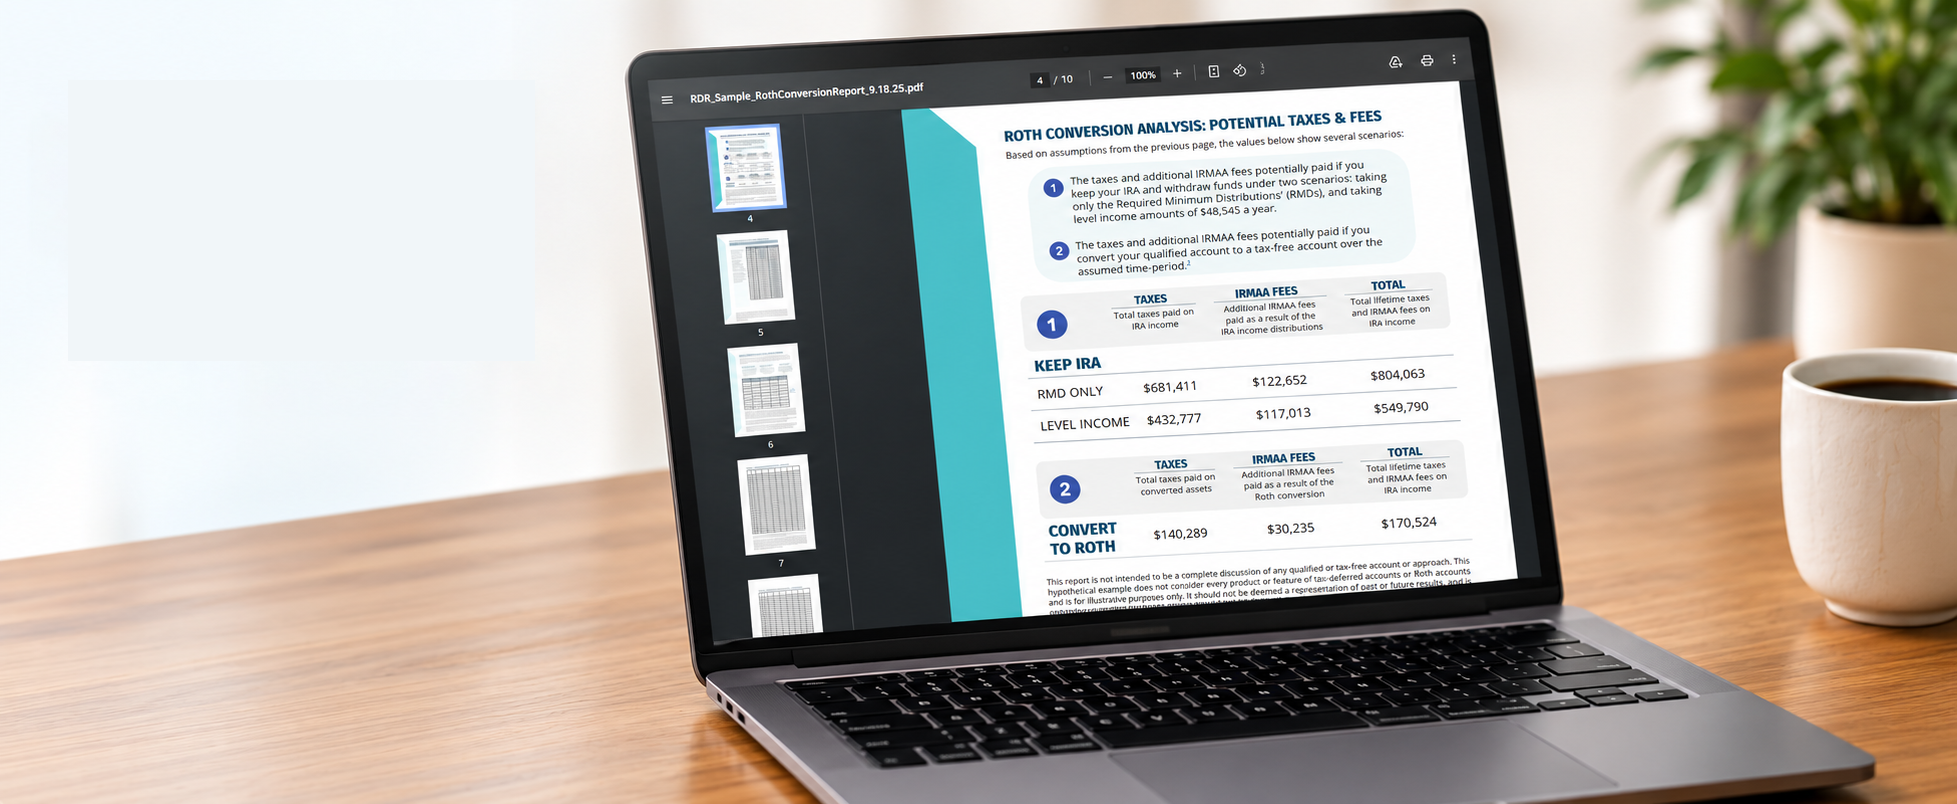
Roth Done RightTax & IRMAA Analysis
Annuity AlphaFIA vs. Managed Account
Legacy Done RightLife Insurance Analysis
Total Tax BurdenRetirement Tax Snapshot
What’s a message frame?
“Framing” is a common communication technique that targets the audience’s attention on a certain aspect of a broad or complex subject. As this Harvard Business Review article notes, framing can “bring clarity to complexity.”
Financial advisors know the power of bringing clarity to complexity. It’s not enough for us to know what’s right for our clients; the clients have to understand it and believe it, too.
And that’s where message frames come in.
How do I leverage message frames?
Within marketing for financial advisors, message frames often serve as stories or narratives around which we can help a client understand risk and how to address it.
This is especially true when we’re helping clients understand tax risk in retirement. “Taxes” are a broad and complex topic. While many savers understand in theory how rising taxes could impact their retirement income, they don’t really know how to evaluate the impact in practice.
Enter the message frame.
I’ll share one of my favorite message frames on taxes in retirement and then show you how to adapt it to various prospect and client interactions.
Your IRA’s Silent Partner
Do you or someone you know own a small business? I’m a small business owner myself. Running a business can be complicated – and sometimes expensive – so many business owners have a partner.
Let’s say I’m a partner in your small business, and I own 20% of your company.
At the end of each year, as you take a profit from your company, you know you’ll owe me 20% of that profit. After all, I own 20% of your company.
But let’s say next year I come to you and demand 30% of your company’s profit.
What would you say to me?
I suspect you’d say something along the lines of, “Get lost.” “I don’t think so.” Or simply, “No.” Maybe if you were nice, you’d say, “Becky, I know you want 30% of the profits. But you only own 20% of the company. So you’ll get 20% of the profits as planned.”
It’s just common sense.
But here’s something you might not have considered:
If you’ve saved for retirement in a 401(k) IRA, you have a silent partner in your retirement business.
And that partner can change its ownership stake at any time.
That silent partner is the IRS. After all, the IRS gets a piece of every dollar you withdraw from your 401(k) or IRA. They, in a sense, own part of your retirement accounts.
But unlike a small business partner, the IRS can change its ownership at any time by adjusting your tax bracket or tax rate.
And that means this year, the IRS owns 20% of your IRA and next year, legislation gets passed where the IRS owns 30% of your IRA… and there’s nothing you can do about it.
I would never accept a partner in my business who could change his ownership stake without my permission. And I don’t want you to accept that in your retirement approach, either.
Let’s evaluate your current approach and see if there are funds we want to protect from this silent partner and its ever-changing stake in your retirement account.
Putting the Frame to Work
This is one of my favorite frames because it’s extremely effective.
It takes a complex issue (tax variability as it applies to tax-deferred retirement funds) and brings it clarity by relating the issue to something your client already understands (owning a business).
It can also be used across marketing for financial advisors:
In a seminar, workshop, or webinar, as a way to engage the audience and uncover a new risk they hadn’t considered
On radio or TV to tell a story that motivates listeners to learn more about tax diversification
In email marketing, to grab a reader’s attention
As a consumer video on social media or your website to show the kinds of problems you help savers address
In your client meetings, to help relate tax diversification to something the client can easily understand
And on and on
That’s the beauty of message frames. Once you develop a few that you like, you’ll find ways to share them across your client interactions. I’ve used this frame in casual conversations on airplanes and in front of audiences of a thousand people. It always converts because it brings clarity to the complex.
Give this message frame a try, and let me know the kind of response you experience. I’d love to hear your favorite message frames for taxes in retirement, too – connect with me here.
Free Study Group Replay
How Stonewood Advisors Stay Ahead of the Next Planning Conversation.
Watch a recent Stonewood Study Group focused on the legacy planning conversation. You’ll see how Stonewood helps advisors break down timely planning topics, client conversation angles, and practical strategies you can put to use immediately.
Expert insights. Real strategies.
Study Group Replay
Timely planning topics
Real client conversation angles
Practical strategies you can use
Real Advisors. Real Results.
See how advisors are using Stonewood software to win larger cases and deliver better
outcomes for their clients.
An advisor was working with a prospect who was a real "do-it-yourselfer" when it came to Roth conversions.
The client was converting assets up their existing tax bracket – and hadn't considered any impact to
IRMAA.
With Roth Done Right, the advisor was able to show an alternate pattern that sped up the conversion to
6 years. The new structure offered $30,000 savings in conversion taxes – a 20% reduction on the
prospect's conversion tax bill. The report also showed hundreds of thousands of dollars in long-term
tax and IRMAA savings from the converted assets – an amount the prospect hadn't been able to quantify
on his own.
Outcome
A new client with $1M in new AUM, and a $1M FIA sale to fund the conversion process.
An advisor was working with a prospect who already had assets with Ken Fisher. Fisher's team presented a
5% systematic withdrawal projection, so the advisor needed a stronger way to frame the income
conversation.
Using the Annuity Alpha report, the advisor showed how an annuity could deliver over 8% in annual cash
flow with lifetime income, plus a long-term care doubler. The contrast was clear enough that the prospect
moved forward.
Outcome
$1.5M placed and a $100K in new business revenue.
An advisor was working with a 58-year-old couple with an established, well-funded retirement income plan,
leaving an additional $3M IRA to build out a legacy for the kids. The couple's existing advisor had no
real additional plan for this money, other than to keep it in their managed account and grow that money as
much as possible for the kids.
Using the Legacy Done Right report, the advisor showed the need for tax planning on this $3M IRA.
According to the advisor, the simple analysis "opened up the wallet" to the Roth conversion story. The
advisor then used the blended Roth/Life feature in the report to show a blend of Roth Conversion assets
with some Life Insurance to help maximize the client’s legacy.
Outcome
$3M in motion. The advisor picked up a $1.5M FIA sale that will be converted to Roth. And the advisor
also sold a 5-Pay Protection focused IUL policy at $225,000 of premium per year.
An advisor group incorporated the Total Tax Burden report into the strategy presentation for all new
prospects. They ran the tax snapshot for every new client as part of their first meeting conversation,
quantifying the growing tax burden of IRA money – and illustrating the kinds of tax savings possible
when working with their firm.
Starting in January of 2023, this simple analysis was presented to every single prospect who walked in
the door. The goal was to differentiate their practice and drive overall revenue growth through various
Roth conversion strategies.
Outcome
From 2022 to 2025, new annual AUM rose from $5M to $50M. Annual FIA sales rose from $3M to $35M.
And annual life premium rose from $50K to $1M.