By: Becky Swansburg
Halloween is a good reminder that this year is coming to an end, and it is time to check which prospect conversations have gone quiet.
Think about the person who attended your seminar, registered for a webinar, or requested information about Roth conversions. You invested in starting that relationship. A thoughtful follow-up gives it somewhere to go.
As the calendar moves toward Thanksgiving and December commitments, build your financial advisor marketing plan around the interest those prospects have already shown. Connect a question they care about with something useful and a clear next step.
Organize leads around their interests
Review your recent seminar, webinar, and website leads. Group them by what they actually asked about or requested: retirement taxes, income planning, market risk, or leaving a legacy.
Use conversation notes and registration details where you have them. When someone’s interest is unclear, ask which retirement question is most relevant to them now.
A person who asked about managing IRA withdrawals should receive a message connected to that question. Someone concerned about supporting a surviving spouse deserves a conversation about that priority.
Choose one useful resource for each group
Select a resource that helps someone understand their next decision. That could be a brief educational video, a retirement tax calculator, or a checklist of questions to discuss before leaving full-time work.
For prospects approaching retirement with substantial savings, explain how the resource relates to their planning stage. If you use an estimate or illustration, make its assumptions clear.
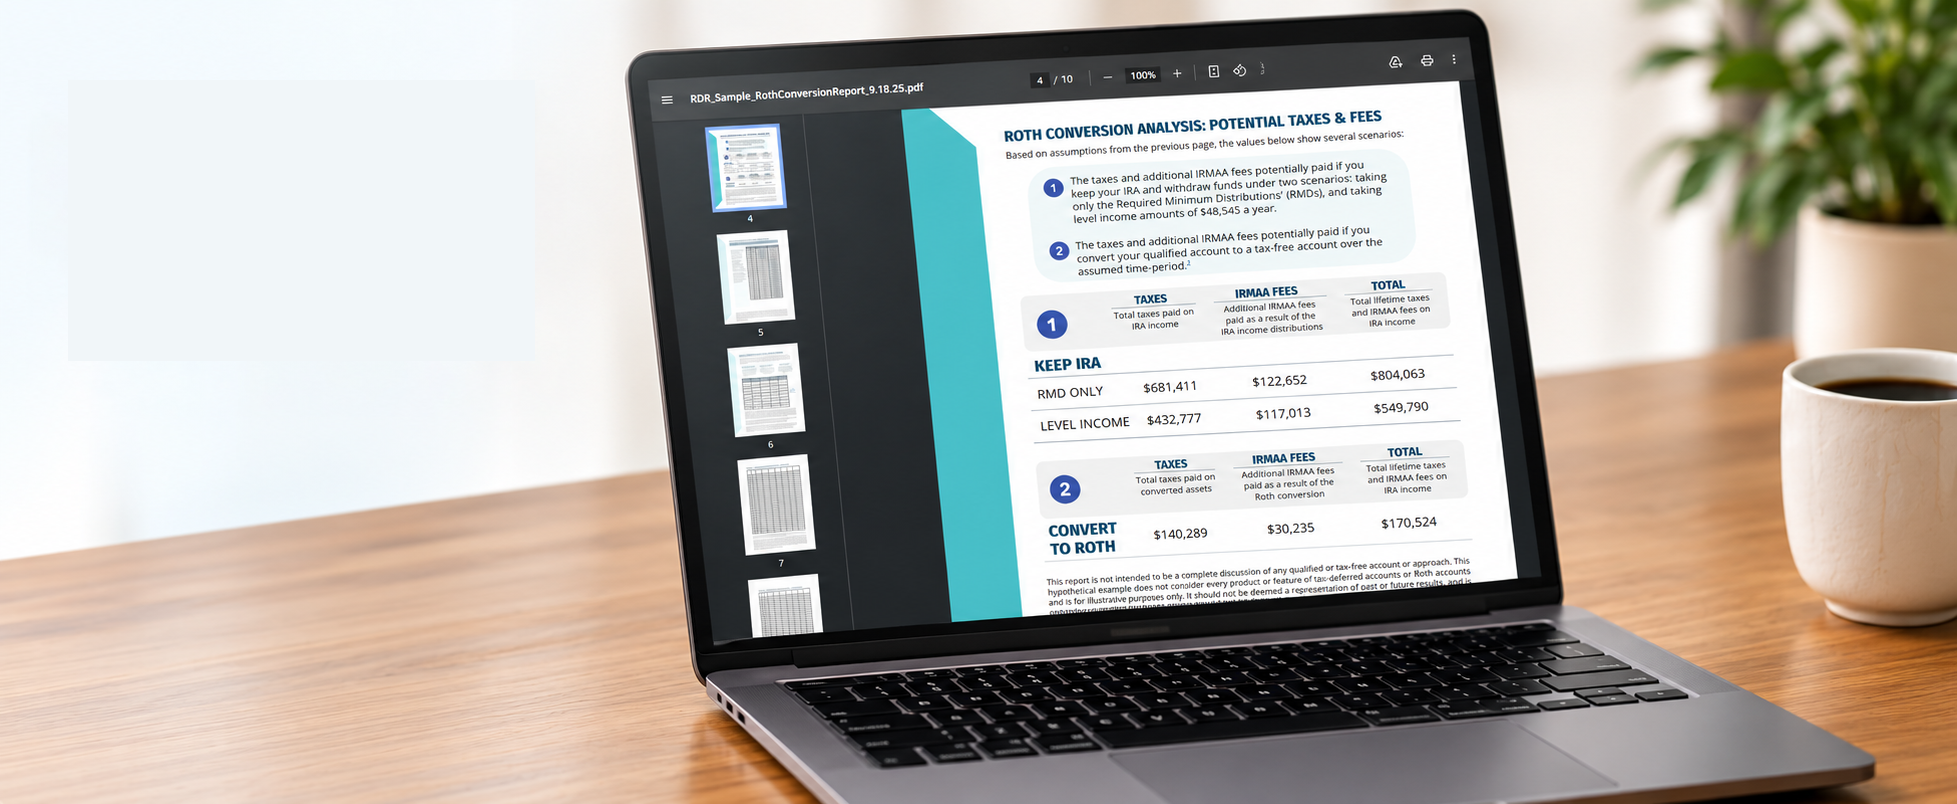
For example, our Retirement Tax Bill calculator can introduce a discussion about potential retirement taxes. Our follow-up guide shows ways to use it with event attendees and people who registered but could not attend. Want a sample? Connect with us here.
Build three purposeful touches
Give each message its own job. A sequence over several weeks can look like this:
First touch: Reopen the conversation.
Reference the event or question that brought you together, then share the relevant resource.
“You asked about how IRA withdrawals could affect your retirement income. I thought this overview would be useful as you think about your next steps.”
Second touch: Ask a focused question.
Follow up with a question that is easy to answer.
“Have you started mapping out which accounts you would use for income when you retire?”
Third touch: Offer a specific conversation.
Explain what a meeting would cover.
“We could walk through your current income plan and identify the questions that need a closer look before year-end.”
Once someone responds, use their answer to guide the next conversation and adjust any scheduled follow-up messages.
Make the next step easy to understand
A prospect should know why they would meet with you. Describe the question you will explore, what they should bring, and what they can expect to learn.
Choose one action for each message: reply with a question, view a resource, or schedule a conversation. Match that action to where the person is in the relationship.
Track the conversations your marketing creates
Review replies, meetings scheduled, meetings attended, and the topics people raise. Record the agreed next step so useful conversations keep moving.
Those observations can also inform your next seminar, webinar, or newsletter. If several prospects ask the same question, you have a practical subject to address.
Give your quiet leads a reason to hear from you this fall. Start with the conversation they already wanted to have.