In prospect meetings
As you’re discussing tax-related retirement planning topics, the Widow’s Penalty can educate your clients on the impact of tax changes in retirement - opening meaningful tax conversations.
Fast. Simple. Insightful.
See how the Widow's Penalty could affect your client's after-tax retirement income.
The Widow’s Penalty shows your clients the higher tax rate they pay going forward - potentially impacting the surviving spouse’s after-tax wealth.
As you’re discussing tax-related retirement planning topics, the Widow’s Penalty can educate your clients on the impact of tax changes in retirement - opening meaningful tax conversations.
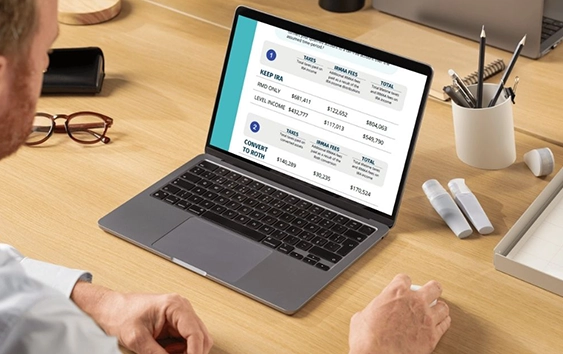
When modeling Roth conversions for your clients, the Widow’s Penalty can help evaluate the total tax savings of a conversion. (Looking for software to help model your clients’ Roth conversion - Widow’s Penalty included? Check out Stonewood’s Roth Done Right software.)
Talking taxes in your group marketing events? Use this analysis to include a hypothetical example of how the Widow’s Penalty could impact a sample client - and invite your audience to meet with you to see their own Widow’s Penalty.
Once clients see how much the surviving spouse’s tax rate could increase, the conversation changes. They want to know what they can do today.
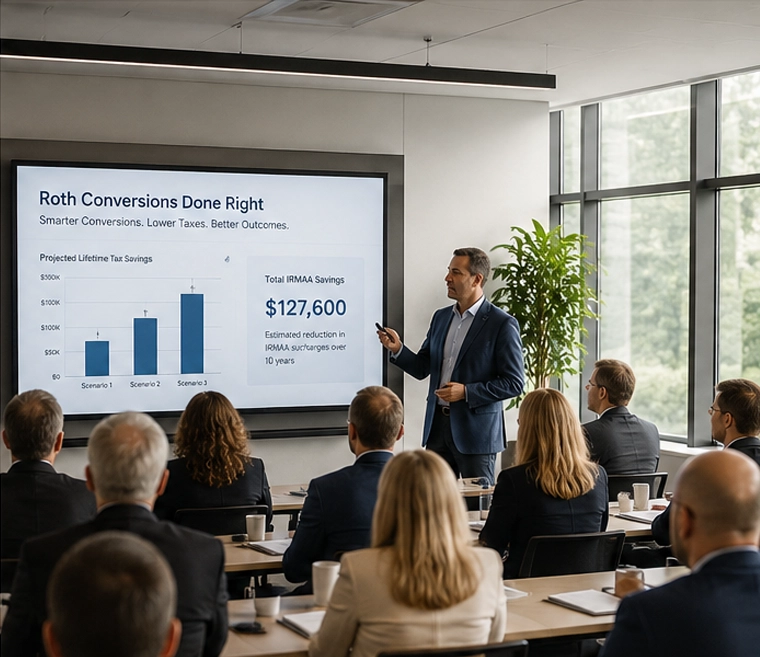
Stonewood’s Roth Done Right software helps you model Roth conversions leveraging your client's current joint-filing bracket. Clients can compare tax and IRMAA savings for multiple conversion scenarios and structures. The best part? You can run their report in under 60 seconds - no tax return needed.
It’s the effective tax rate increase a surviving spouse faces when they switch from filing jointly to filing as single. The brackets compress to roughly half the width, the standard deduction drops from $32,200 to $16,100 (2026, per IRS Rev. Proc. 2025-32), and the same income, or less, gets taxed harder. You already know this. Your clients usually don’t until it happens.
It takes total household income, runs it through the 2026 federal brackets and standard deductions for both MFJ and Single, and computes the effective tax rate for each. The widow’s penalty is the percentage increase: (Single rate minus MFJ rate) divided by MFJ rate.
Absolutely. The numbers generated from this calculator can be used in client discussions and meetings.
Converting traditional IRA assets to a Roth while both spouses are alive uses the wider MFJ brackets. Tax gets paid at today’s known rate. Roth distributions don’t show up as taxable income later, which can help keep the surviving spouse in a lower bracket, reduce future RMDs, and lower provisional income for Social Security taxation and IRMAA.
It can. IRMAA uses a 2-year lookback on income. The single-filer threshold drops to $109,000 compared to $218,000 for couples (2026, per CMS). A client who was comfortably below the joint threshold can land in a higher premium tier as a single filer, even on less income. This calculator focuses on the federal tax piece, but it’s worth flagging IRMAA in the full planning conversation.
Just the couple’s current total household income. If income changes when one spouse dies (lost SS check, pension stops), toggle the switch and enter the adjusted amount. No tax return, no detailed breakdown needed.
The widow’s penalty can lead to broader questions about Roth conversions, retirement income, annuities, legacy planning and future taxes.
Stonewood’s suite of signature tools - Roth Done Right, Annuity Alpha, Legacy Done Right and the Retirement Tax Bill calculator - can help you connect those issues and show clients a clear path forward.
One connected toolkit. Better explanations. More productive client conversations.